Going Direct
One lender. One set of criteria.
- One lender to consider
- One credit policy
- Limited finance structures
- You manage the process yourself
- No wider lender comparison
One finance check. Compare motorcycle loan options across 70+ lenders - matched to your profile. No impact on your credit score. No obligation.
The same straightforward process, every time — no matter what you’re financing.
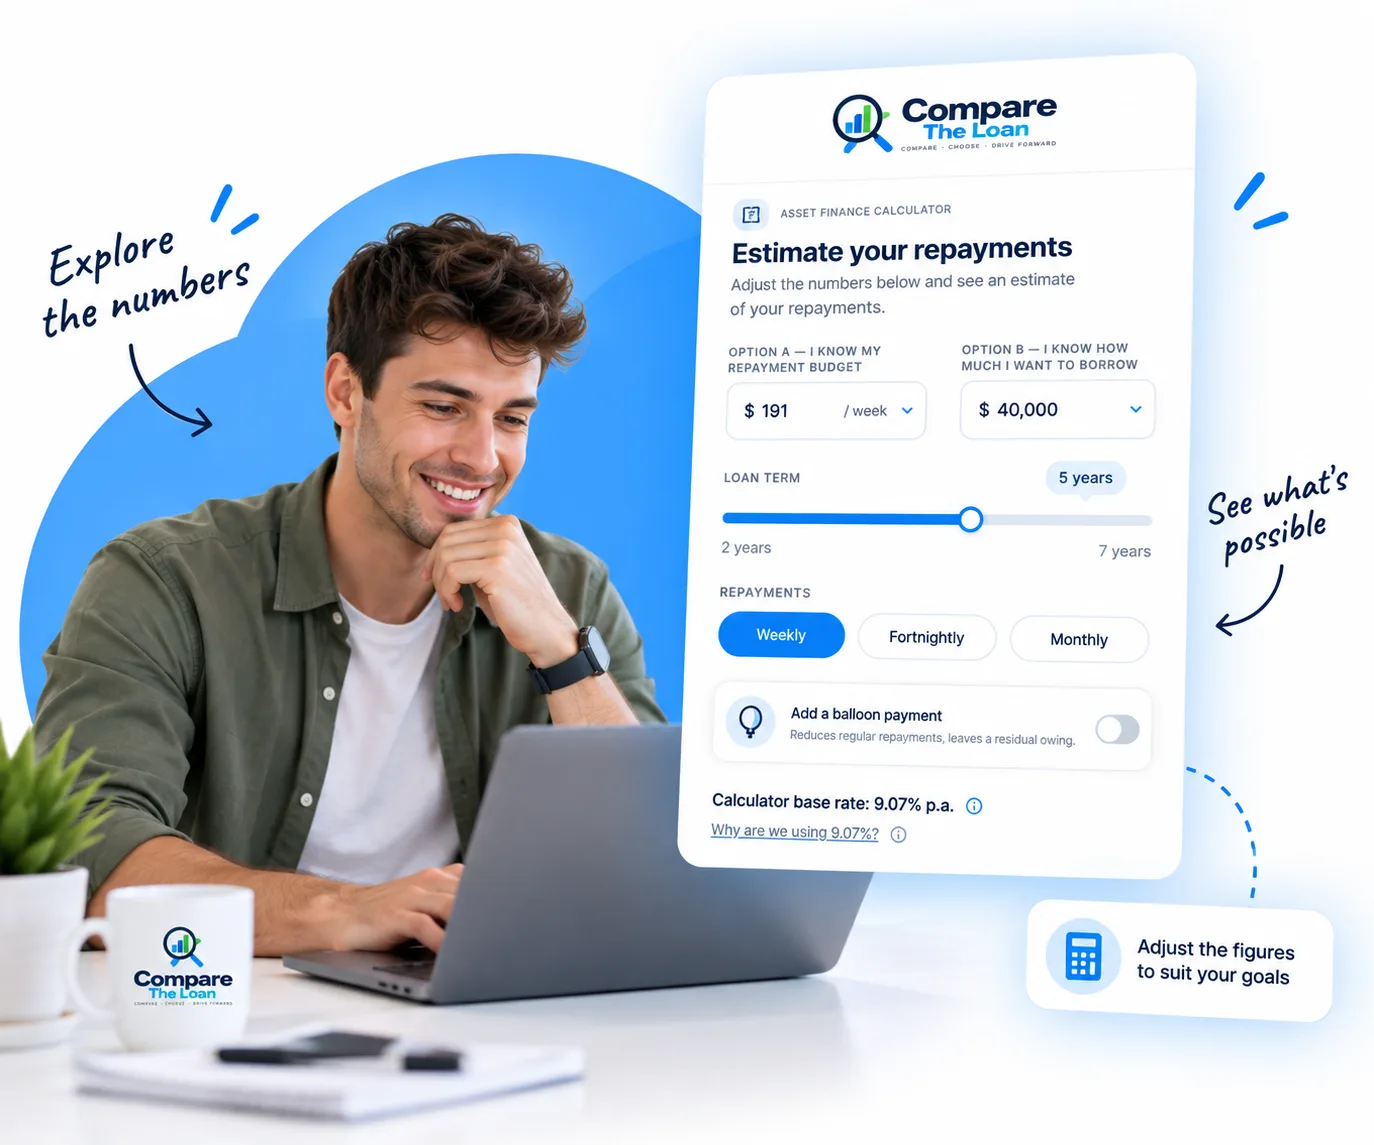
Explore a few scenarios before you compare — adjust the loan amount, term and repayment frequency to see how the numbers could look.
Adjust the numbers below — the estimate updates instantly.
Base rate vs comparison rate
Base rate is the interest rate applied to the loan balance. Comparison rate includes the base rate plus most fees and charges, giving a more realistic all-in cost when comparing loans.
This calculator uses a base rate for estimates. When comparing loan options, consider the comparison rate as well.
This calculator uses a fixed 9.07% p.a. base rate as a general personal-lending benchmark, based on Reserve Bank of Australia Personal Lending Rates data. It is not an average rate specifically for car, boat, caravan or other asset finance.
The rate you receive may be higher or lower depending on your credit profile, asset, loan structure and lender.
Figure referenced: F8, updated monthly by the RBA.
Source: RBA Statistical Tables – Personal Lending Rates (F8) →$191/ week
Nice! You've found your comfort zone.
Now let's compare 70+ lenders to discover your borrowing power, rates and repayments.
No impact on your credit score
Checking your options won't affect your credit score.
Disclaimer: This calculation is a guide only and is based on limited information provided, excluding fees and charges. It does not constitute loan approval or a recommendation. Actual rates, fees and repayments depend on your circumstances and information verified during assessment. A balloon payment reduces regular repayments but leaves an amount payable at the end of the loan term.
The same motorcycle loan product, compared across 70+ lenders, whichever purchase scenario applies to you.
A motorcycle loan may suit Brisbane riders buying new, used or privately, whether for commuting, weekend riding, or business use.
For new or used motorcycle purchases for personal use or commuting, including self-employed applicants who can provide tax returns instead of payslips.
For motorcycles bought privately, where a PPSR check using the VIN is worth doing to confirm the bike isn't recorded as stolen, written off, or carrying existing finance.
A genuine but secondary use case: some lenders structure motorcycle finance as commercial or ABN finance for courier or delivery work, particularly for businesses with an established trading history.
Using a motorcycle loan broker in Brisbane lets you compare motorcycle loan options from multiple lenders instead of being limited to one lender's products and lending criteria. Compare The Loan compares your profile across 70+ lenders to identify options that may suit your circumstances, with a licensed finance broker helping you understand your options before you decide whether to proceed.
Going Direct
One lender. One set of criteria.
Compare The Loan
One enquiry. 70+ lenders to compare.
We're currently collecting reviews from Brisbane motorcycle loan customers — check back soon.
Customer reviews coming soon.
Customer reviews coming soon.
Customer reviews coming soon.
Compare The Loan launched five years ago, but it's backed by Sean Burt's 26+ years of Brisbane broking experience and close to 2,000 completed applications. Every enquiry is compared across 70+ lenders with a soft credit check first — no branch visit required.
From cruisers and adventure bikes to scooters, new or used.
A loan secured against the bike can mean a lower rate than unsecured finance.
Compare your options across 70+ lenders without a hard credit check.
Built on Sean Burt's long-standing finance broking career.
Compare The Loan is a Brisbane-based finance broker helping riders compare motorcycle loan options right across South East Queensland - from Redland City's bayside commuter suburbs and island communities, to Logan City's Brisbane-Gold Coast commuter corridor, to Ipswich's fast-growing Ripley and Springfield growth areas. Wherever you're riding, we compare your options across a panel of 70+ lenders.
Compare Motorcycle Loan OptionsYou don't need to use a dealership's in-house finance to get a great deal. We arrange finance for motorcycles bought new, used or privately, anywhere across our service area, comparing 70+ lenders regardless of where you found your bike.
Buying brand new? We arrange your finance independently of the dealer's own offer.
Financing a used motorcycle through a licensed dealer works the same way, wherever you're buying from.
Buying privately? We can still help, with a PPSR check to protect you before you pay.
Common questions about comparing motorcycle loans with Compare The Loan.
Motorcycle finance is a loan used to buy a new or used motorcycle, repaid through regular instalments over an agreed term. It can be secured against the bike or arranged as an unsecured personal loan, depending on the lender and the motorcycle's value. Covers road bikes, cruisers, adventure bikes and scooters. Secured loans generally have lower rates because the motorcycle is used as security.
Yes, used motorcycles can be financed, whether purchased from a dealer or through a private sale. Lenders will typically consider the bike's age, condition and value as part of the assessment. Some lenders set maximum age or value limits on motorcycles they'll accept as security, which can affect which lenders suit a particular used bike.
No — finance approval and holding a motorcycle licence are separate matters. A rider still needs the appropriate state or territory licence (such as Queensland's RE or R class) to legally ride the motorcycle once it's financed. Licensing is administered by state and territory transport authorities and sits outside the finance process entirely; a lender approving a loan does not check or confirm licensing status.
Yes, motorcycles used for business purposes such as courier or delivery work can sometimes be financed as commercial or ABN finance rather than a personal loan. This is more likely where the business has an established trading history. A lender assessing commercial use will typically look at business income, time trading and existing commitments alongside the usual personal credit and asset checks.
It can be either, depending on the lender and the motorcycle's value. Secured finance uses the motorcycle as collateral and generally attracts a lower interest rate; unsecured finance doesn't tie the loan to the asset but usually costs more. The choice can depend on the age and value of the motorcycle, since some lenders won't secure loans against older or lower-value bikes.
Typically photo ID, proof of income, recent bank statements, and details of the motorcycle such as make, model, year and VIN, along with a purchase quote, dealer invoice or private sale contract. Business-use applications may additionally require ABN details and recent business bank statements.
The Personal Property Securities Register (PPSR) allows a search by VIN or chassis number to check whether money is owing on a motorcycle, or whether it's recorded as stolen or written off. This is a common step in due diligence for private sales. A PPSR search does not disclose the exact amount owing, ownership history or odometer readings — it's a security-interest and status check, not a full vehicle history report.
The interest rate, comparison rate, loan term, any fees, and whether the loan is secured or unsecured all affect the total cost. A balloon or residual payment can lower regular repayments but adds a lump sum due at the end of the term. Comparing the comparison rate (not just the advertised interest rate) gives a more accurate like-for-like view across different lenders' offers.
Engine capacity can be a factor lenders consider as part of their overall risk and asset assessment, alongside the motorcycle's age and value. It isn't usually a standalone eligibility rule but forms part of the broader picture a lender builds of the asset being financed.
Compare car, boat, caravan, motorcycle, equipment and personal loan options across 70+ lenders — with a licensed finance broker on hand and no obligation to proceed.